Mutual Fund Nominee: How to Add One and What Happens to Your Investments If You Pass Away
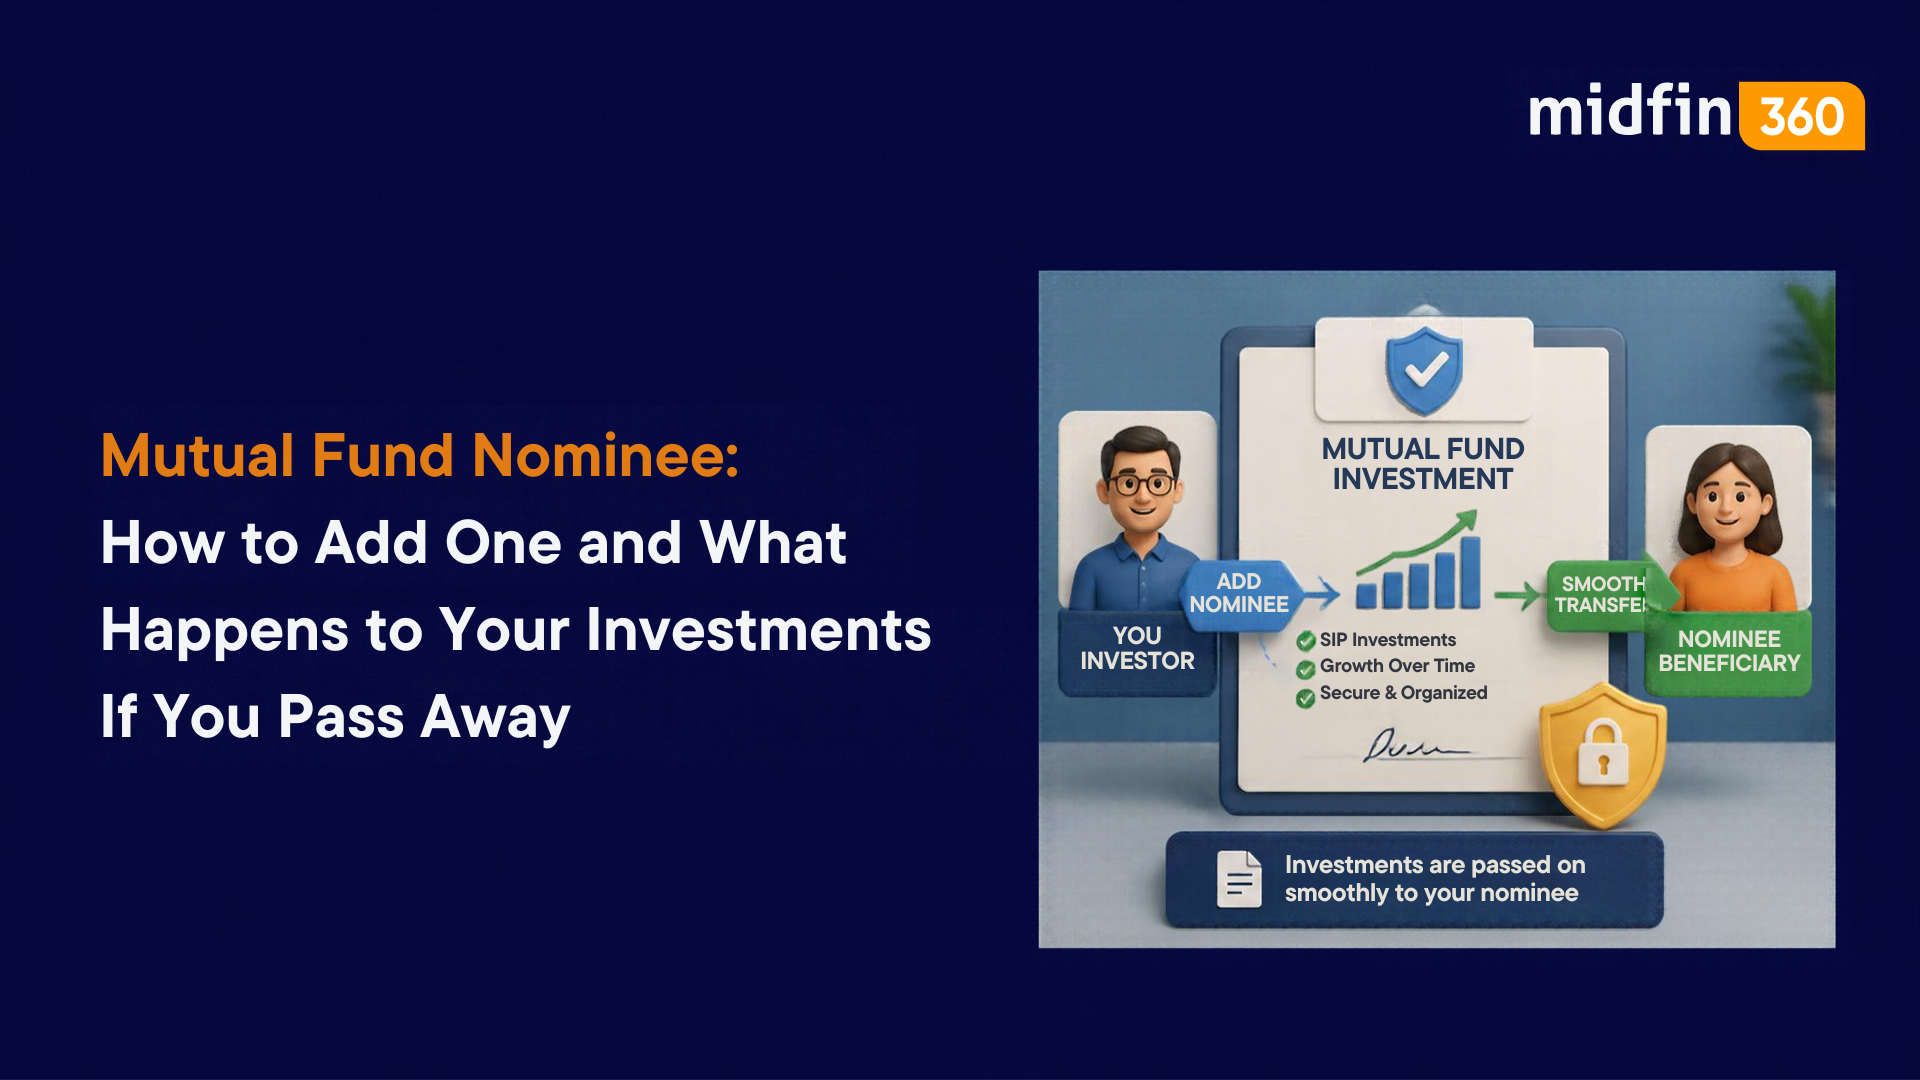
When we start our wealth-creation journey, our focus is entirely on the future. We meticulously track returns, carefully balance our asset allocation, and diligently set up our automated monthly investments. However, in the pursuit of building a multi-crore corpus for our family's financial freedom, we often overlook a critical administrative step that dictates exactly what happens to that wealth if the unforeseen occurs.
Losing a loved one is an emotionally devastating experience. The absolute last thing a grieving family needs is to navigate a complex, bureaucratic maze to access the funds left behind for their care. This is why properly declaring a mutual fund nominee is not just a regulatory checkbox; it is a fundamental act of care and financial responsibility.
If you are currently setting up your investments and wondering about the mutual fund nomination rules 2026, or if you need to know exactly what happens to mutual funds after death, you are in the right place. In this comprehensive, empathetic guide, we will decode the critical nominee vs legal heir mutual fund distinction, explain how to add nominee in mutual fund, outline the mutual fund transmission process, and provide clarity on how to safeguard your family's financial future.
(Disclaimer: The information provided in this guide is for educational purposes. Estate planning and succession rules can be legally complex. We highly recommend consulting a qualified legal professional or Chartered Accountant for advice specific to your family's estate.)
The Core Concept: Nominee vs Legal Heir Mutual Fund
Before diving into the process, it is vital to clear up a common legal misconception. Many investors assume that whoever they name as a nominee automatically becomes the absolute legal owner of the money after their death. Under Indian law, this is not entirely accurate.
Understanding the nominee vs legal heir mutual fund dynamic is crucial:
- The Nominee: A nominee is a person appointed by the investor to receive the mutual fund units upon the investor's death. However, in the eyes of the law, the nominee is generally considered a trustee or a custodian of the assets. Their job is to receive the funds from the Asset Management Company (AMC) and hold them until the rightful legal heirs claim them.
- The Legal Heir: A legal heir is the person entitled to inherit the assets based on the deceased’s legally executed will, or if there is no will, according to the applicable succession laws (e.g., the Hindu Succession Act).
In many families, the nominee and the legal heir are the same person (like a spouse or a child). However, if they are different, the legal heir can legally claim the proceeds from the nominee. Nominating someone ensures that the AMC releases the funds quickly without freezing the account for years in probate court.
Mutual Fund Nomination Rules 2026: What You Need to Know
To protect investors' families and reduce the massive amount of unclaimed money sitting in the financial system, the Securities and Exchange Board of India (SEBI) has heavily streamlined nomination regulations. Here are the key mutual fund nomination rules 2026 you must be aware of:
1. The Mandatory Declaration
SEBI has made it mandatory for all individual investors to make a definitive choice regarding their folios. When you open a new mutual fund account, you must declare a nominee. If you absolutely do not want to name one, you must formally submit a mutual fund nomination opt out declaration. You cannot simply leave the section blank.
2. How Many Nominees in Mutual Fund Can You Have?
You might encounter outdated articles online mentioning "up to 10 nominees." This is incorrect for mutual funds. If you are wondering how many nominees in mutual fund you can legally appoint, the current standard is a maximum of three nominees per mutual fund folio. You can also specify the exact percentage share each nominee should receive (e.g., Spouse 50%, Child A 25%, Child B 25%). If you do not specify a percentage, the AMC will distribute the assets equally among the named nominees.
3. Mutual Fund Nominee for Minor
You can absolutely appoint a minor (a child under 18 years of age) as your nominee. However, because a minor cannot legally manage financial contracts, the mutual fund nominee for minor rule dictates that you must simultaneously appoint an adult guardian. You must provide the guardian's name, their relationship to the minor, and their date of birth.
If you are a parent structuring your investments for your child's future, ensuring the nomination is correctly formatted during your Know Your Customer (KYC) onboarding is essential. To understand how to set up your foundational investments flawlessly, explore our guide on how to start investing in mutual funds a beginner's guide.
How to Add Nominee in Mutual Fund (and How to Change It)
If you have been investing for a few years and realize you left your nomination details empty, you need to act immediately. The process of how to add nominee in mutual fund has been completely digitized and simplified.
Can I Change Nominee in Mutual Fund Online?
Yes, absolutely. The question "can I change nominee in mutual fund online" is one of the most frequently asked, and the answer is a resounding yes. You do not need to visit an AMC office physically.
You can update or add your nominee details through:
- Your Mutual Fund App/Distributor: If you invest through an AMFI-registered distributor platform like midfin360, your foundational eKYC process includes capturing these details securely.
- The AMC Website: You can log in directly to the specific AMC’s portal using your PAN and Folio number to update your nomination.
- Centralized Portals: Registrar and Transfer Agents (RTAs) like CAMS or KFintech offer online portals where you can update your nominee details across multiple mutual fund houses simultaneously using a simple OTP-based authentication.
If you are setting up a Systematic Investment Plan (SIP) today, checking the nominee status should be an automatic part of your routine. We highlight these essential administrative checks in our guide on how systematic investment plans (SIPs) work.
What Happens to Mutual Funds After Death? The Transmission Process
Understanding what happens to mutual funds after death removes the fear of the unknown. When an investor passes away, the mutual fund units are not automatically sold or liquidated. Instead, the ownership of the units is transferred to the surviving holders or nominees.
This legal transfer of units upon death is known as the mutual fund transmission process.
The complexity of the transmission depends entirely on how the mutual fund was held. Let's break down the three most common scenarios:
Scenario 1: Joint Holder Mutual Fund Nomination
If the mutual fund was held jointly by two people (e.g., husband and wife) with the holding mode set to "Anyone or Survivor," the process is incredibly smooth. Upon the death of the primary holder, the surviving joint holder automatically becomes the sole legal owner of the mutual fund units.
The surviving holder simply submits a joint holder mutual fund nomination transmission request along with a notarized copy of the death certificate, and the AMC updates the records. The surviving holder can then continue the investments or redeem them.
Scenario 2: Single Holding with a Registered Nominee
If the deceased was the sole owner of the mutual funds but had clearly registered a nominee, the mutual fund transmission process is straightforward. The nominee must approach the AMC or the distributor to initiate the claim. The units will be transmitted directly into a new folio created under the nominee's name.
Scenario 3: Single Holding Without a Registered Nominee
This is the nightmare scenario you must avoid. If a sole investor dies without a registered nominee, the legal heirs must go through a lengthy, expensive legal process to claim the funds. The AMC will require strict legal documentation, such as a probated Will, a Succession Certificate issued by a competent court, or a Legal Heirship Certificate, depending on the value of the assets. This process can take months or even years.
Mutual Fund Nominee Documents Required After Death
When a nominee initiates a transmission, the AMC requires specific paperwork to prevent fraud and ensure compliance with AMFI transmission guidelines. While exact requirements can vary slightly between fund houses, the standard mutual fund nominee documents required after death typically include:
- A formal Transmission Request Form (TRF) filled out by the nominee.
- The original Death Certificate (or a copy duly notarized/attested by a Gazetted Officer).
- The nominee’s PAN Card and updated KYC status.
- A cancelled cheque of the nominee’s bank account (where future redemptions will be credited).
- Foreign Account Tax Compliance Act (FATCA) declaration by the nominee.
Note: Once the units are transmitted to the nominee, the original SIPs of the deceased are immediately cancelled. If the nominee wishes to generate a monthly income from the newly transmitted corpus, they must set up a fresh mandate. You can learn how to structure this effectively in our guide on how SWP explained helps create monthly income.
The midfin360 Advantage: Securing Your Family's Future
Wealth creation is a deeply personal endeavor, and protecting that wealth requires robust systems and trustworthy guidance. A critical part of knowing what is AMFI-registered and why it matters is understanding the safeguards a regulated distributor provides.
At midfin360 (AMFI-registered ARN-306591), we believe that financial security goes beyond just tracking your XIRR. We offer access exclusively to regular mutual fund plans because they inherently include the dedicated, human support of a professional distributor.
When you onboard through our KRA-based eKYC system, we ensure your nomination details are captured securely from day one. If tragedy strikes, your family doesn't have to navigate faceless call centers or decipher complex jargon alone. Our Relationship Managers stand by your loved ones, providing the compassionate guidance needed to navigate the mutual fund transmission process efficiently.
Furthermore, because true financial security requires a holistic approach, we always recommend securing a robust life cover alongside your mutual funds. You can explore the profound necessity of pure protection in our guide on term insurance vs life insurance in India, and browse secure options on our dedicated insurance platform.
Conclusion
Naming a mutual fund nominee is perhaps the most important five-minute task in your entire financial journey. It is the ultimate act of financial care for your family, ensuring that the wealth you spent a lifetime building is transferred to them seamlessly, without legal friction or emotional distress.
By understanding the mutual fund transmission process, keeping your KYC updated, and adhering to the mutual fund nomination rules 2026, you build an airtight financial fortress. Whether you are wondering what happens to mutual funds after death or looking to align your retirement distribution strategy (which we cover deeply in our safe withdrawal retirement guide), you do not have to navigate these complexities alone. Partnering with a professional, AMFI-registered distributor ensures your family is supported in every season of life.
Ready to build a secure, properly structured wealth portfolio with expert guidance?
Explore the midfin360 app and see how our team can support your wealth journey today.
Frequently Asked Questions
Manage all from your mobile
Take charge of your finances seamlessly — only on the Midfin360 app