Got a Diwali Bonus? Smart Ways to Invest It (Without Regretting It by January)
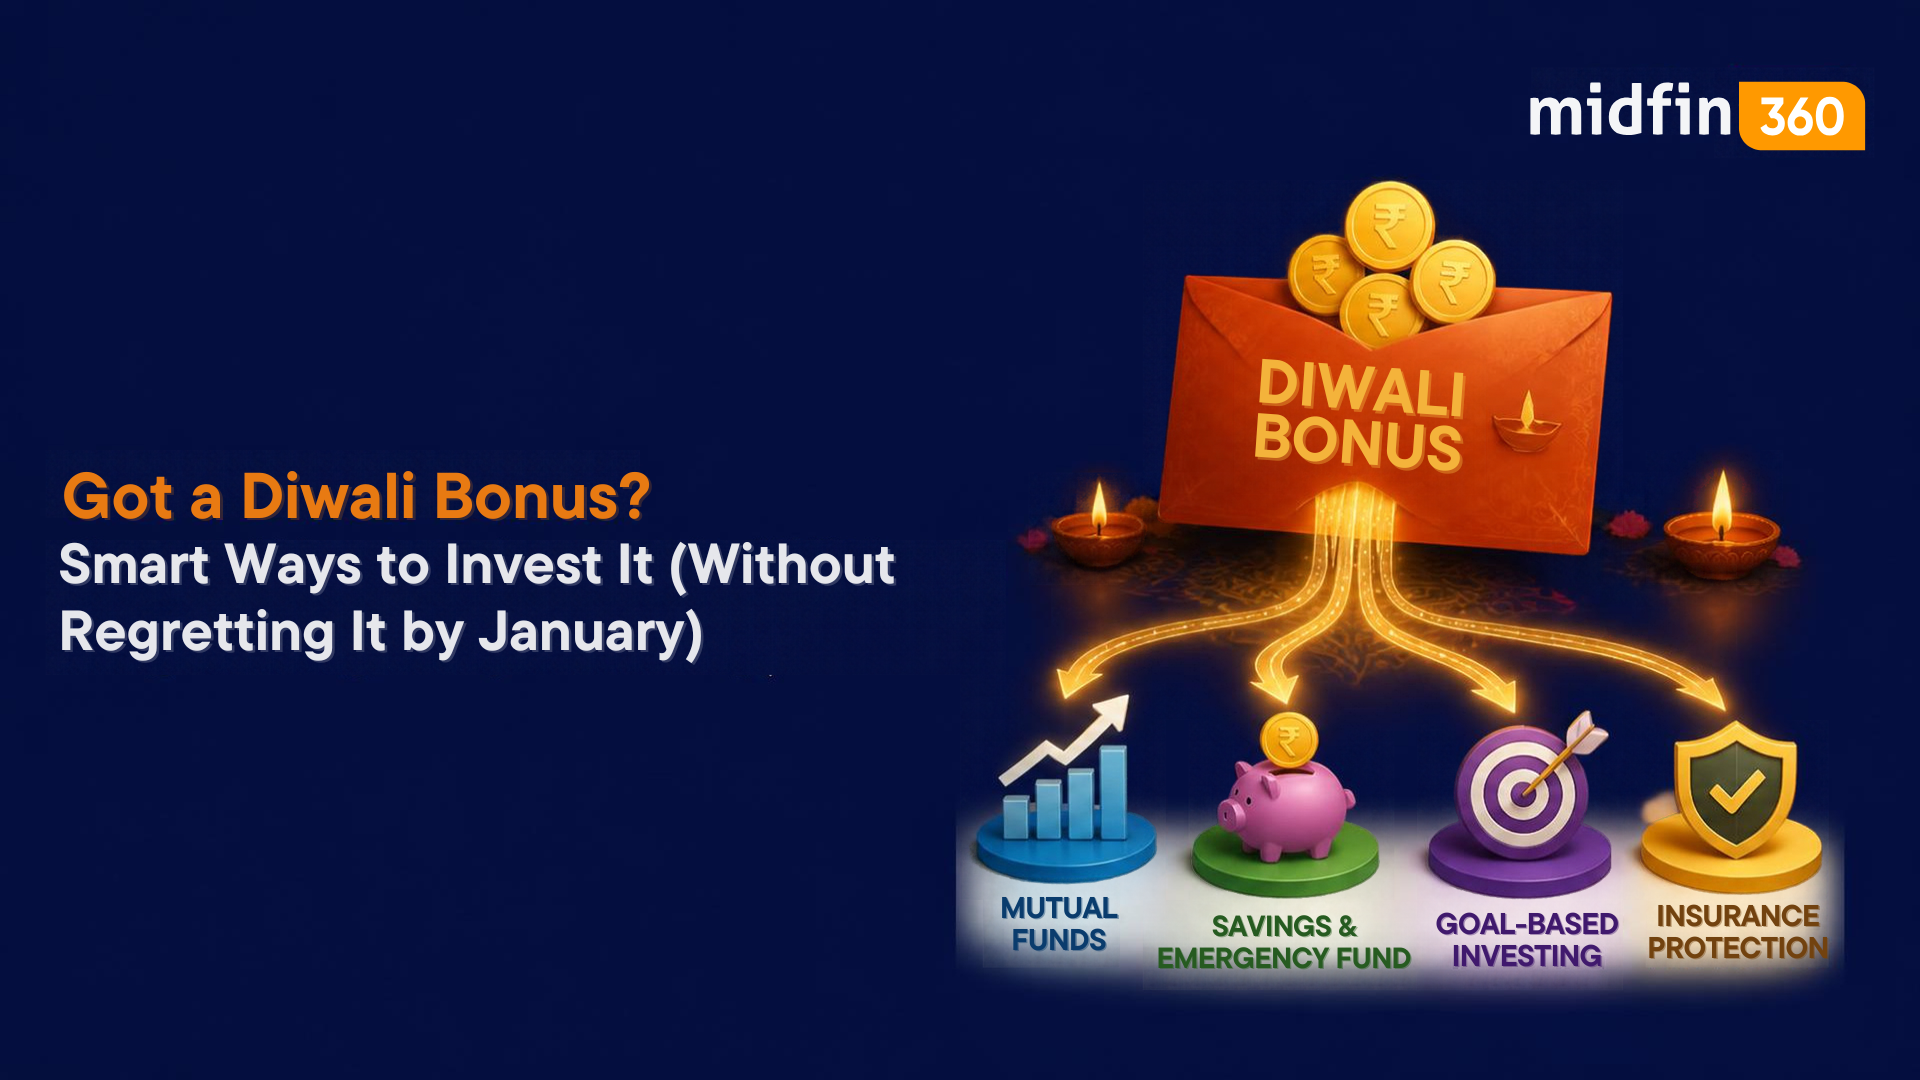
The festive season of Diwali brings with it a sense of joy, cultural celebration, and for millions of professionals across the country, the highly anticipated annual bonus. With the Diwali bonus 2026 expected to hit bank accounts in late October (just ahead of the main festival on November 8), the excitement is palpable.
When you see a significant lump sum credited to your account, the immediate human instinct is to celebrate. Your mind races with ideas: upgrading your smartphone, booking a luxury vacation, or going on a massive shopping spree. While there is absolutely nothing wrong with enjoying the fruits of your labor, letting the entire windfall slip through your fingers often leads to a severe case of "buyer's remorse" a few months later.
If you are currently holding your payslip and wondering exactly how to invest Diwali bonus without squandering it, you are at a critical financial crossroads. The decisions you make over the next few weeks can either fund a fleeting weekend of luxury or lay the foundation for decades of financial freedom.
In this comprehensive guide, we will explore exactly what to do with bonus money India, answer the classic bonus money emergency fund or invest dilemma, break down the mechanics of lumpsum vs SIP vs STP, and provide actionable bonus investment ideas for salaried employees so you can celebrate the festival of wealth responsibly.
The Reality Check: Taxes and Festive Spending
Before we dive into wealth creation, we must address the reality of your bonus payout. A bonus is not "free money" in the eyes of the government; it is a component of your salary.
According to the Income Tax Act of India, your bonus is fully taxable as "Income from Salary." Your employer will likely deduct Tax Deducted at Source (TDS) based on your applicable income tax slab before the money even reaches you. Therefore, always base your financial planning on the net amount you receive, not the gross figure on your appraisal letter. (Consult your Chartered Accountant to understand your exact tax liabilities).
Secondly, a robust financial plan is not about absolute deprivation. It is perfectly reasonable to allocate 10% to 20% of your bonus for genuine festive celebrations, gifting, or honoring traditions. If you plan to allocate a portion of your bonus toward festive gold purchases, ensure you do it smartly by reading our guide on Dhanteras 2026 gold investment rather than paying massive making charges on physical jewelry.
For the remaining 80%, you need a structured framework to determine how to invest a windfall.
Step 1: Clear the Toxic Debt First
If you are searching for how to invest 1 lakh bonus, your first step shouldn't be the stock market if you are carrying high-interest debt.
Credit card outstanding balances and unsecured personal loans often carry interest rates ranging from 15% to 36% annually. There is absolutely no regulated financial instrument—not even the most aggressive mutual fund—that can guarantee returns high enough to outpace the devastating compounding of credit card debt. Use your bonus to clear these toxic liabilities immediately. This is the highest guaranteed "return on investment" you will ever make.
Step 2: Bonus Money Emergency Fund or Invest?
Once your bad debt is cleared, the next priority is securing your foundation. If you are caught in the bonus money emergency fund or invest debate, the answer is always the emergency fund first.
Life is unpredictable. Without a 3-to-6-month safety net of liquid cash, a sudden medical emergency or job transition will force you to break your long-term investments prematurely. If your safety net is currently empty, use your bonus to fund it. You can learn exactly how to park this money efficiently by reading our detailed breakdown on how to build an emergency fund with liquid funds, ensuring your cash remains accessible without losing value to inflation.
Step 3: The Protection Check
Before deploying capital into the markets, you must ensure your family is protected against the ultimate worst-case scenario. If you do not have adequate life insurance, a portion of your bonus should be used to pay the annual premium for a pure term life insurance policy.
Always keep your insurance and investments separate. We explain the profound mathematical benefits of this approach in our comparison of term insurance vs life insurance in India. Once you understand the mechanics, you can seamlessly secure your family's future through the dedicated midfin360 insurance platform.
Step 4: Bonus Investment Ideas for Salaried Employees
If your debt is cleared, your emergency fund is full, and your life cover is active, you are finally ready to deploy your Diwali bonus 2026 toward pure wealth creation.
Here are the most effective bonus investment ideas for salaried employees:
1. Maximize Your Tax-Saving Options (Section 80C)
If you haven't yet exhausted your ₹1.5 Lakh limit under Section 80C, your bonus is the perfect tool to close the gap. Instead of scrambling in March, deploy your bonus now into an Equity Linked Savings Scheme (ELSS). ELSS funds offer a dual advantage: immediate tax savings and long-term equity growth, locked in for just three years. Review our updated tax-saving mutual funds ELSS guide to align this with your current financial year goals.
2. Boost Your Retirement Corpus
You can utilize your bonus to secure an exclusive, additional tax deduction of ₹50,000 under Section 80CCD(1B) by investing in the National Pension System (NPS) regulated by the PFRDA. This is a brilliant way to simultaneously lower your tax burden and aggressively fund your golden years.
3. Ask: Should I Invest Bonus in Mutual Funds?
For any capital left over, the answer to "should I invest bonus in mutual funds" is a resounding yes. Broad-based equity mutual funds act as the primary growth engine of your portfolio, specifically designed to generate the high, inflation-beating returns necessary to build generational wealth. If you have been relying solely on low-yield instruments, read our eye-opening post on can mutual funds beat inflation? to understand why market-linked products are essential.
How to Invest a Windfall: Lumpsum vs SIP vs STP
Deciding what to invest in is only half the strategy. Deciding how to deploy the capital is where many investors falter. If you are staring at a massive sum and wondering how to invest a lumpsum safely, you must navigate the lumpsum vs SIP vs STP dilemma carefully.
The stock market is highly volatile, and the fear of investing a lump sum right before a market crash is very real. To understand how to manage your emotions during these peaks, review our guide on the psychology of investing and staying calm during market volatility.
Here is a factual breakdown of your deployment options:
1. The Lumpsum Route
Mathematically, if you are investing for a 15-to-20-year horizon in a market that consistently rises over the long term, deploying your entire bonus as a lump sum on day one often yields the highest return because all your capital starts compounding immediately. However, this requires immense emotional fortitude to ignore short-term crashes.
2. The Systematic Transfer Plan (STP for Bonus Money)
If you cannot stomach the risk of poor timing, an STP is your best friend. A Systematic Transfer Plan (STP) allows you to park your entire bonus in a safe, low-volatility Liquid Fund or Ultra-Short Duration fund. From there, a fixed amount is automatically transferred into your chosen high-growth Equity Fund every month.
Using an STP for bonus money triggers rupee cost averaging—buying more units when markets are low and fewer when they are high—acting as an emotional shock absorber.
(Important Note on STP Taxation: According to the Securities and Exchange Board of India (SEBI), every STP installment is legally treated as a redemption from the source fund and a new purchase into the target fund, triggering potential capital gains tax on the debt fund's profits. We detail the mechanics of managing this tax friction in our piece on how to switch funds without losing tax benefits.)
3. The SIP Route
Alternatively, you can leave your bonus in your bank account and initiate a new Systematic Investment Plan (SIP) to slowly deploy the capital over the next six months. If you prefer this simpler route, learn exactly how systematic investment plans (SIPs) work.
Structuring the Goal: Choosing the Right Asset Allocation
When executing your plan on how to invest Diwali bonus, your time horizon dictates your asset allocation.
- Goal < 3 Years: Do not touch equity. Use your bonus to buy safe Corporate Fixed Deposits or Short-Duration Debt Funds.
- Goal 3 to 5 Years: Explore Balanced Advantage or Aggressive Hybrid Funds to cushion market shocks.
- Goal 5+ Years: Lean heavily into Flexi-Cap, Large-Cap, or Mid-Cap equity funds for maximum wealth creation.
If you are unsure how to balance these categories, our comprehensive guide on equity, debt, hybrid: choosing the right fund type will clarify the exact risk-reward profile of each bucket.
(Taxation Reality Check: Remember that equity investments are subject to Long-Term Capital Gains (LTCG) and Short-Term Capital Gains (STCG) taxes. Stay prepared by keeping our mutual fund capital gains tax calendar bookmarked.)
The midfin360 Advantage for Your Diwali Bonus
Determining exactly what to do with bonus money India is a deeply personal exercise. Leaving a massive bonus to sit idle in a savings account is a mistake, but deploying it blindly without a strategy is even worse. Many DIY investors start a new investment with a bonus, only to panic-sell it three months later when the market corrects. You can see how these behavioral traps destroy wealth in our analysis of why your SIP is not growing and how to fix common investor mistakes.
This is why midfin360, an AMFI-registered distributor (ARN-306591), champions the regular plan ecosystem. We do not believe in abandoning investors to figure out how to invest a windfall alone.
When you explore mutual funds through our platform, you gain access to a dedicated Relationship Manager. We help you conduct accurate risk profiling, decide the exact mechanics of your lumpsum vs SIP vs STP deployment, and ensure your diversification strategy perfectly aligns with your real-world goals. If you are a young professional looking for a structured blueprint to begin, our mutual funds for beginners 90-days checklist or our breakdown on the best SIP for an INR 25,000 salary are excellent starting points.
Conclusion
Understanding exactly how to invest Diwali bonus is a defining moment in your financial year. While it is incredibly tempting to view your Diwali bonus 2026 as a license to splurge, doing so guarantees that the joy will fade long before January arrives.
By applying a disciplined framework—clearing toxic debt, securing your emergency liquid funds, protecting your family with term insurance, and strategically executing an STP for bonus money—you transform a temporary festive windfall into a permanent pillar of your long-term wealth. You don't have to navigate how to invest a lumpsum safely on your own. Partnering with a professional distributor ensures your bonus works as hard for your future as you did to earn it.
Ready to make your bonus count and build a truly resilient portfolio?
Explore the midfin360 app and connect with our team to start your guided wealth journey today.
Frequently Asked Questions
Manage all from your mobile
Take charge of your finances seamlessly — only on the Midfin360 app